Rethinking BNPL: Credit Innovations for Tomorrow
Sponsored by SAP Fioneer, rock-solid technology to empower banks, insurance companies and challengers to grow and transform at scale and speed.
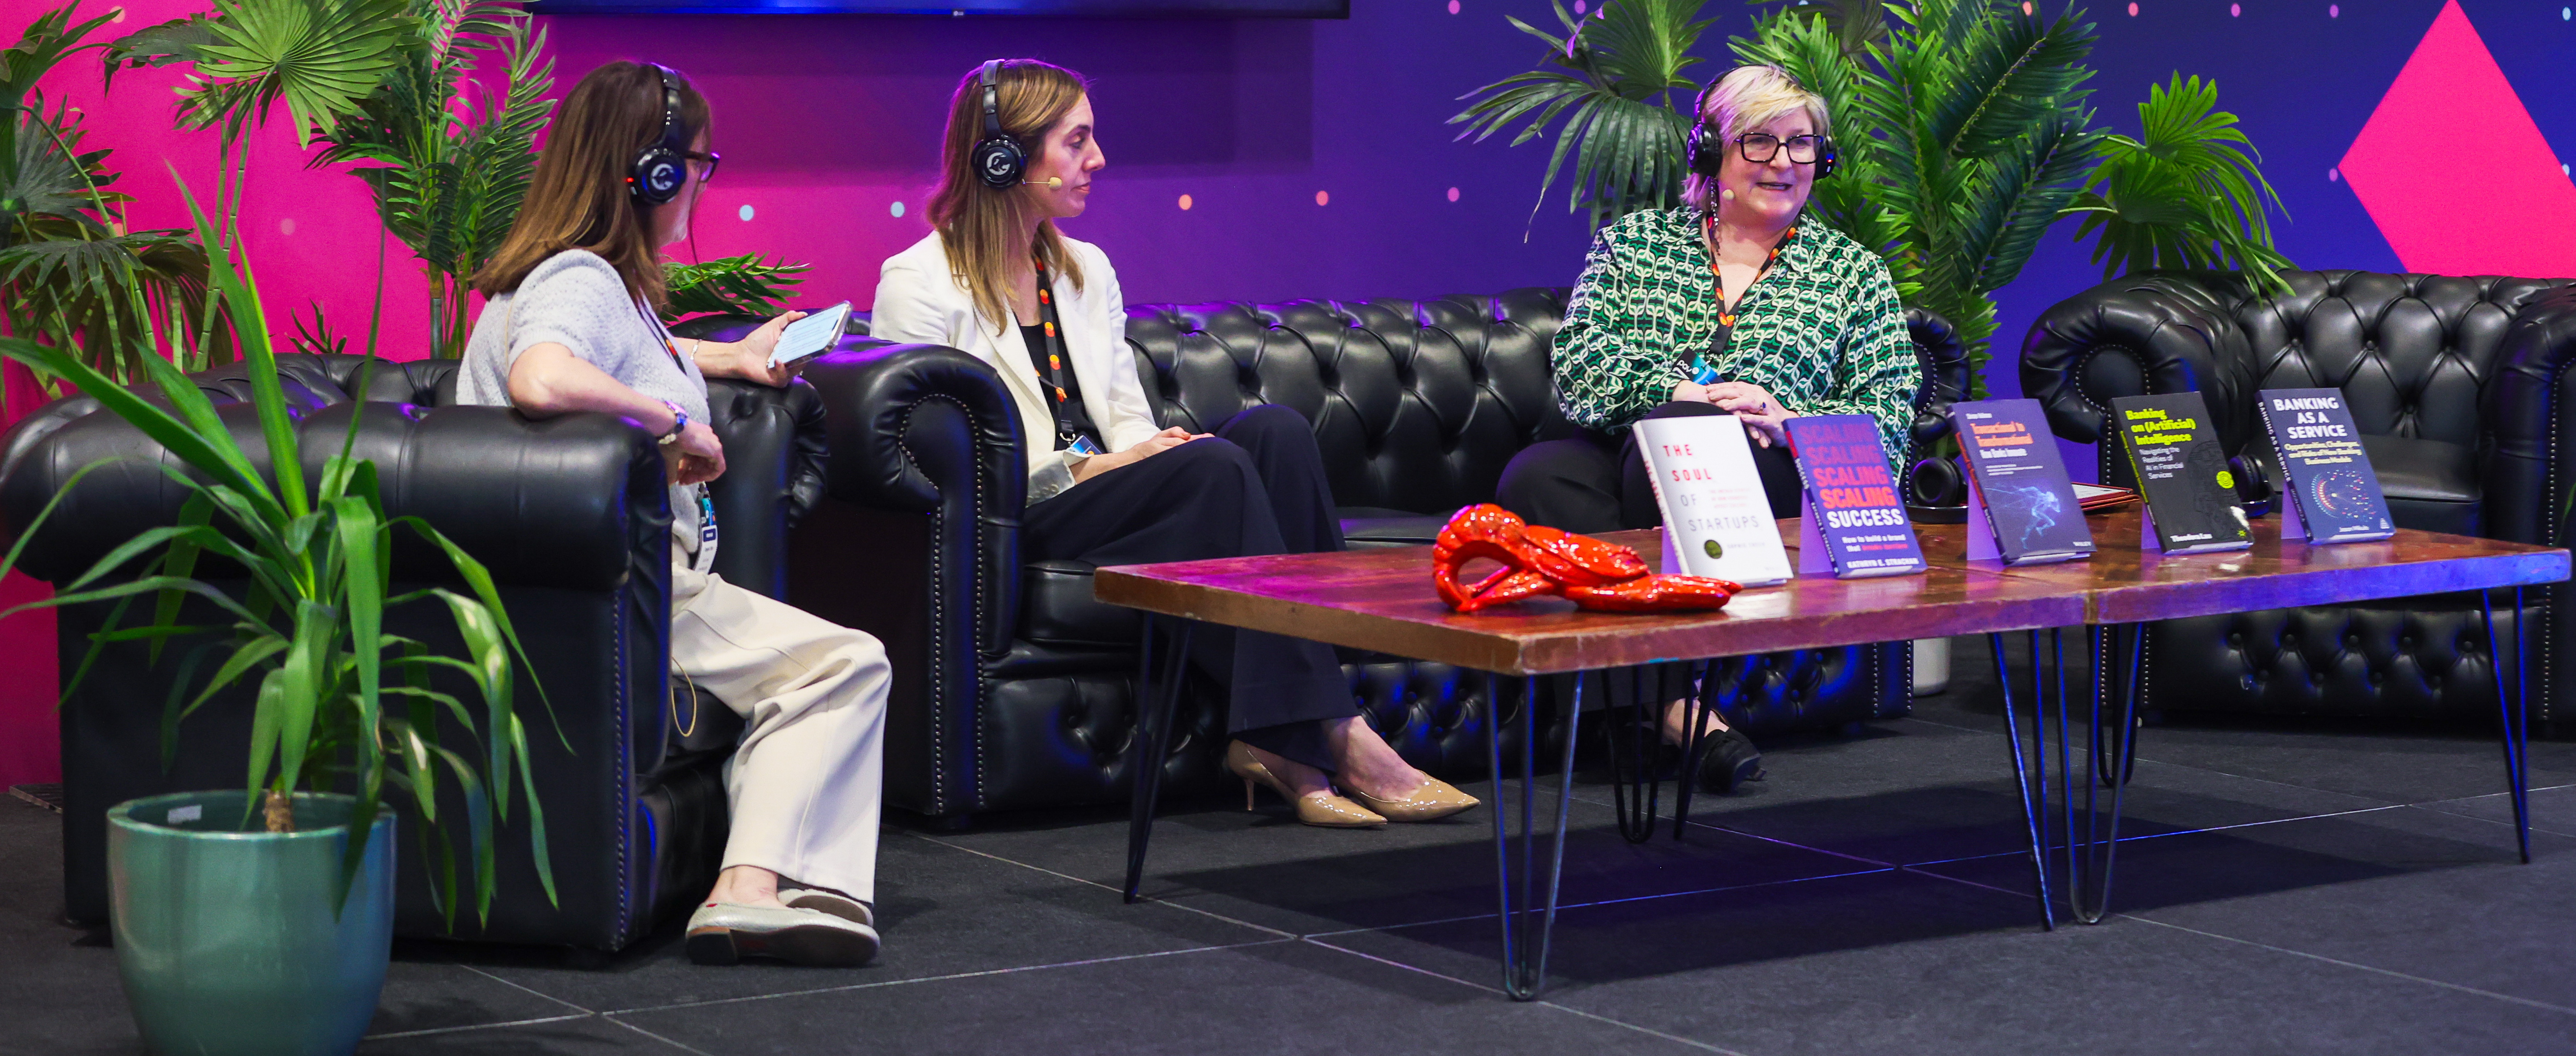
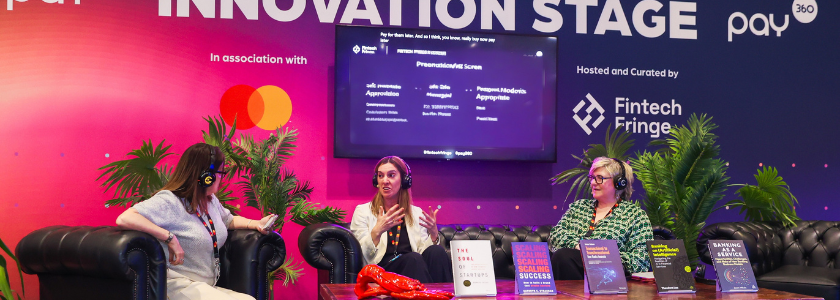
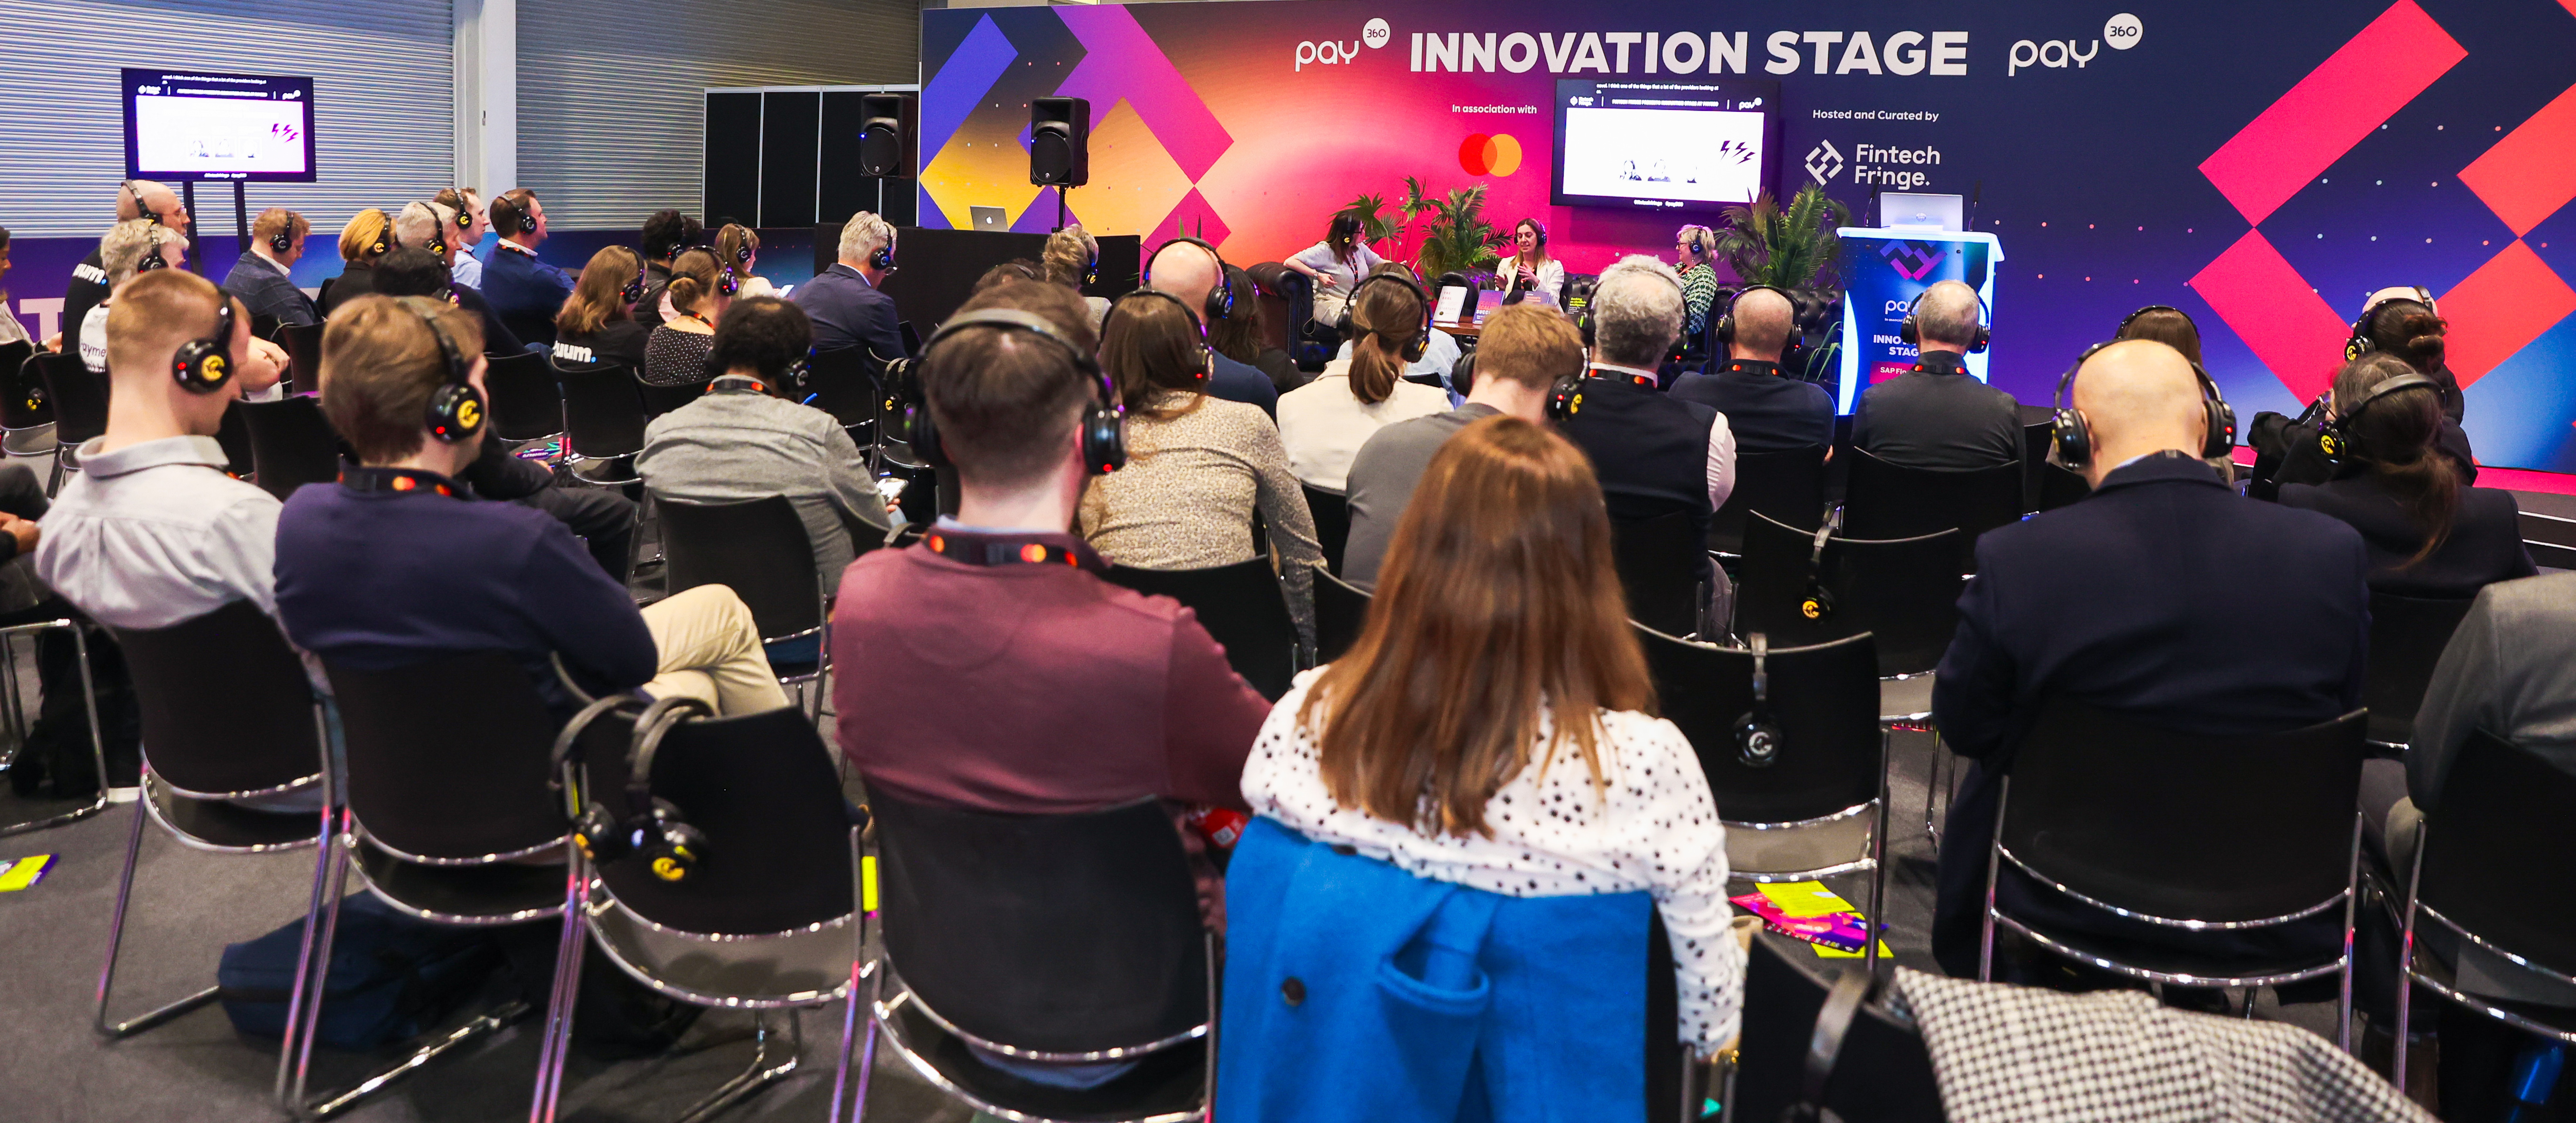
Hosted on the Innovation Stage at Pay360 by Fintech Fringe, this panel took a fresh look at the Buy Now Pay Later (BNPL) revolution. Far from just a payment option, BNPL is transforming into a flexible, embedded credit tool that’s reshaping how consumers and businesses access finance.
Chaired by Angela Yore, SkyParlour, the panel explored use cases, emerging demographics, embedded models, and the future of responsible lending. Featuring:
Melinda Roylett, Managing Director, Merchant Services, Lloyds Bank
Silvia Mensdorff-Pouilly, Head of Business Development EMEA Enterprise, Worldpay
BNPL is Old—But Now It's Everywhere
Both Melinda and Silvia pointed out that BNPL isn't new, it’s simply evolved.
From German catalogue instalments to modern Klarna integrations, what’s changed is seamlessness and scale.
“This is just lay-by with a better UX… Only now it’s digital, instant, and embedded in the checkout.”
Melinda Roylett, Managing Director, Merchant Services, Lloyds Bank
The BNPL Boom: Who's Using It?
According to Silvia, BNPL is a $342 billion global industry. In the UK alone, 7% of online purchases use BNPL up from 1% a decade ago. Women aged 18–34 are the biggest users, often for fashion and electronics. But it's also moving upmarket.
Melinda added
“One in six BNPL users in the UK now earns over £75k .. it’s becoming mainstream.”
Embedded Credit & Responsible Lending
Angela highlighted how BNPL is now offered for everything from takeaway food to designer watches, raising questions about affordability and responsible use.
Melinda stressed the need for guardrails:
“If BNPL is to scale sustainably, it needs strong risk controls.”
Silvia added that Worldpay only partners with BNPL providers that do proper credit checks and fraud prevention:
“Consumer trust and merchant trust go hand in hand.”
From Enterprise to SMBs and B2B
Melinda shared Lloyds’ new Black Horse Flex Pay product, designed to offer embedded finance to SMBs.
“It’s the democratisation of instalment payments,” she said. “Click a button, turn it on.”
Silvia noted that B2B BNPL is also gaining traction, especially in the US, where invoice-based buying is common.
“That’s the next frontier,”
The Future: BNPL as a Feature
In their closing reflections, the panel agreed that BNPL would become increasingly invisible.
Melinda predicted:
“In five years, BNPL won’t be a product, it’ll be a feature,” Something you just expect to see, online or in-store.”
Silvia went further:
“AI will personalise the entire payment journey. Your digital agent will know what you can afford—and recommend the best way to pay.”
Practical Takeaways
BNPL is now mainstream and evolving fast—especially in high-ticket and B2B segments.
Embedded finance is democratising credit access across enterprise, SMBs, and consumers.
Risk and fraud controls are critical to making BNPL work sustainably at scale.
Expect AI to shape how customers choose and use BNPL in the future.