Fighting Financial Crime in Real Time
Faster payments are brilliant until they’re not. Here’s how data, behaviour and collaboration can move quicker than the fraudster – without breaking the seconds promise.
The UK ran roughly five billion faster payments last year, up 13% on the year before. Every one of those transactions clears in seconds, and every one of those seconds is a small window of opportunity for someone with bad intentions. Meanwhile the criminals have new tools of their own: deepfakes, voice clones and social engineering campaigns that now run for months at a time.
The instinct is to slow everything down. The better answer is to get smarter about where you add friction, what data you hold, and how quickly you share what you know. Fraud prevention is not a trade-off against speed – it is a discipline that has to keep pace with it.
Friction in the right place
The seconds promise means a payment has to settle almost instantly, so the work has to happen around it rather than in the middle of it. That starts at onboarding, where the first line of defence often fails first, and continues through to the behavioural signals that betray a fraudulent transaction long before the money moves.
Low-value test payments are a classic tell – a penny in, then a large transfer, or an account that takes a single pound and sits dormant for months before suddenly filling up. A system that can remember that earlier behaviour is worth more than one that simply checks each payment in isolation.
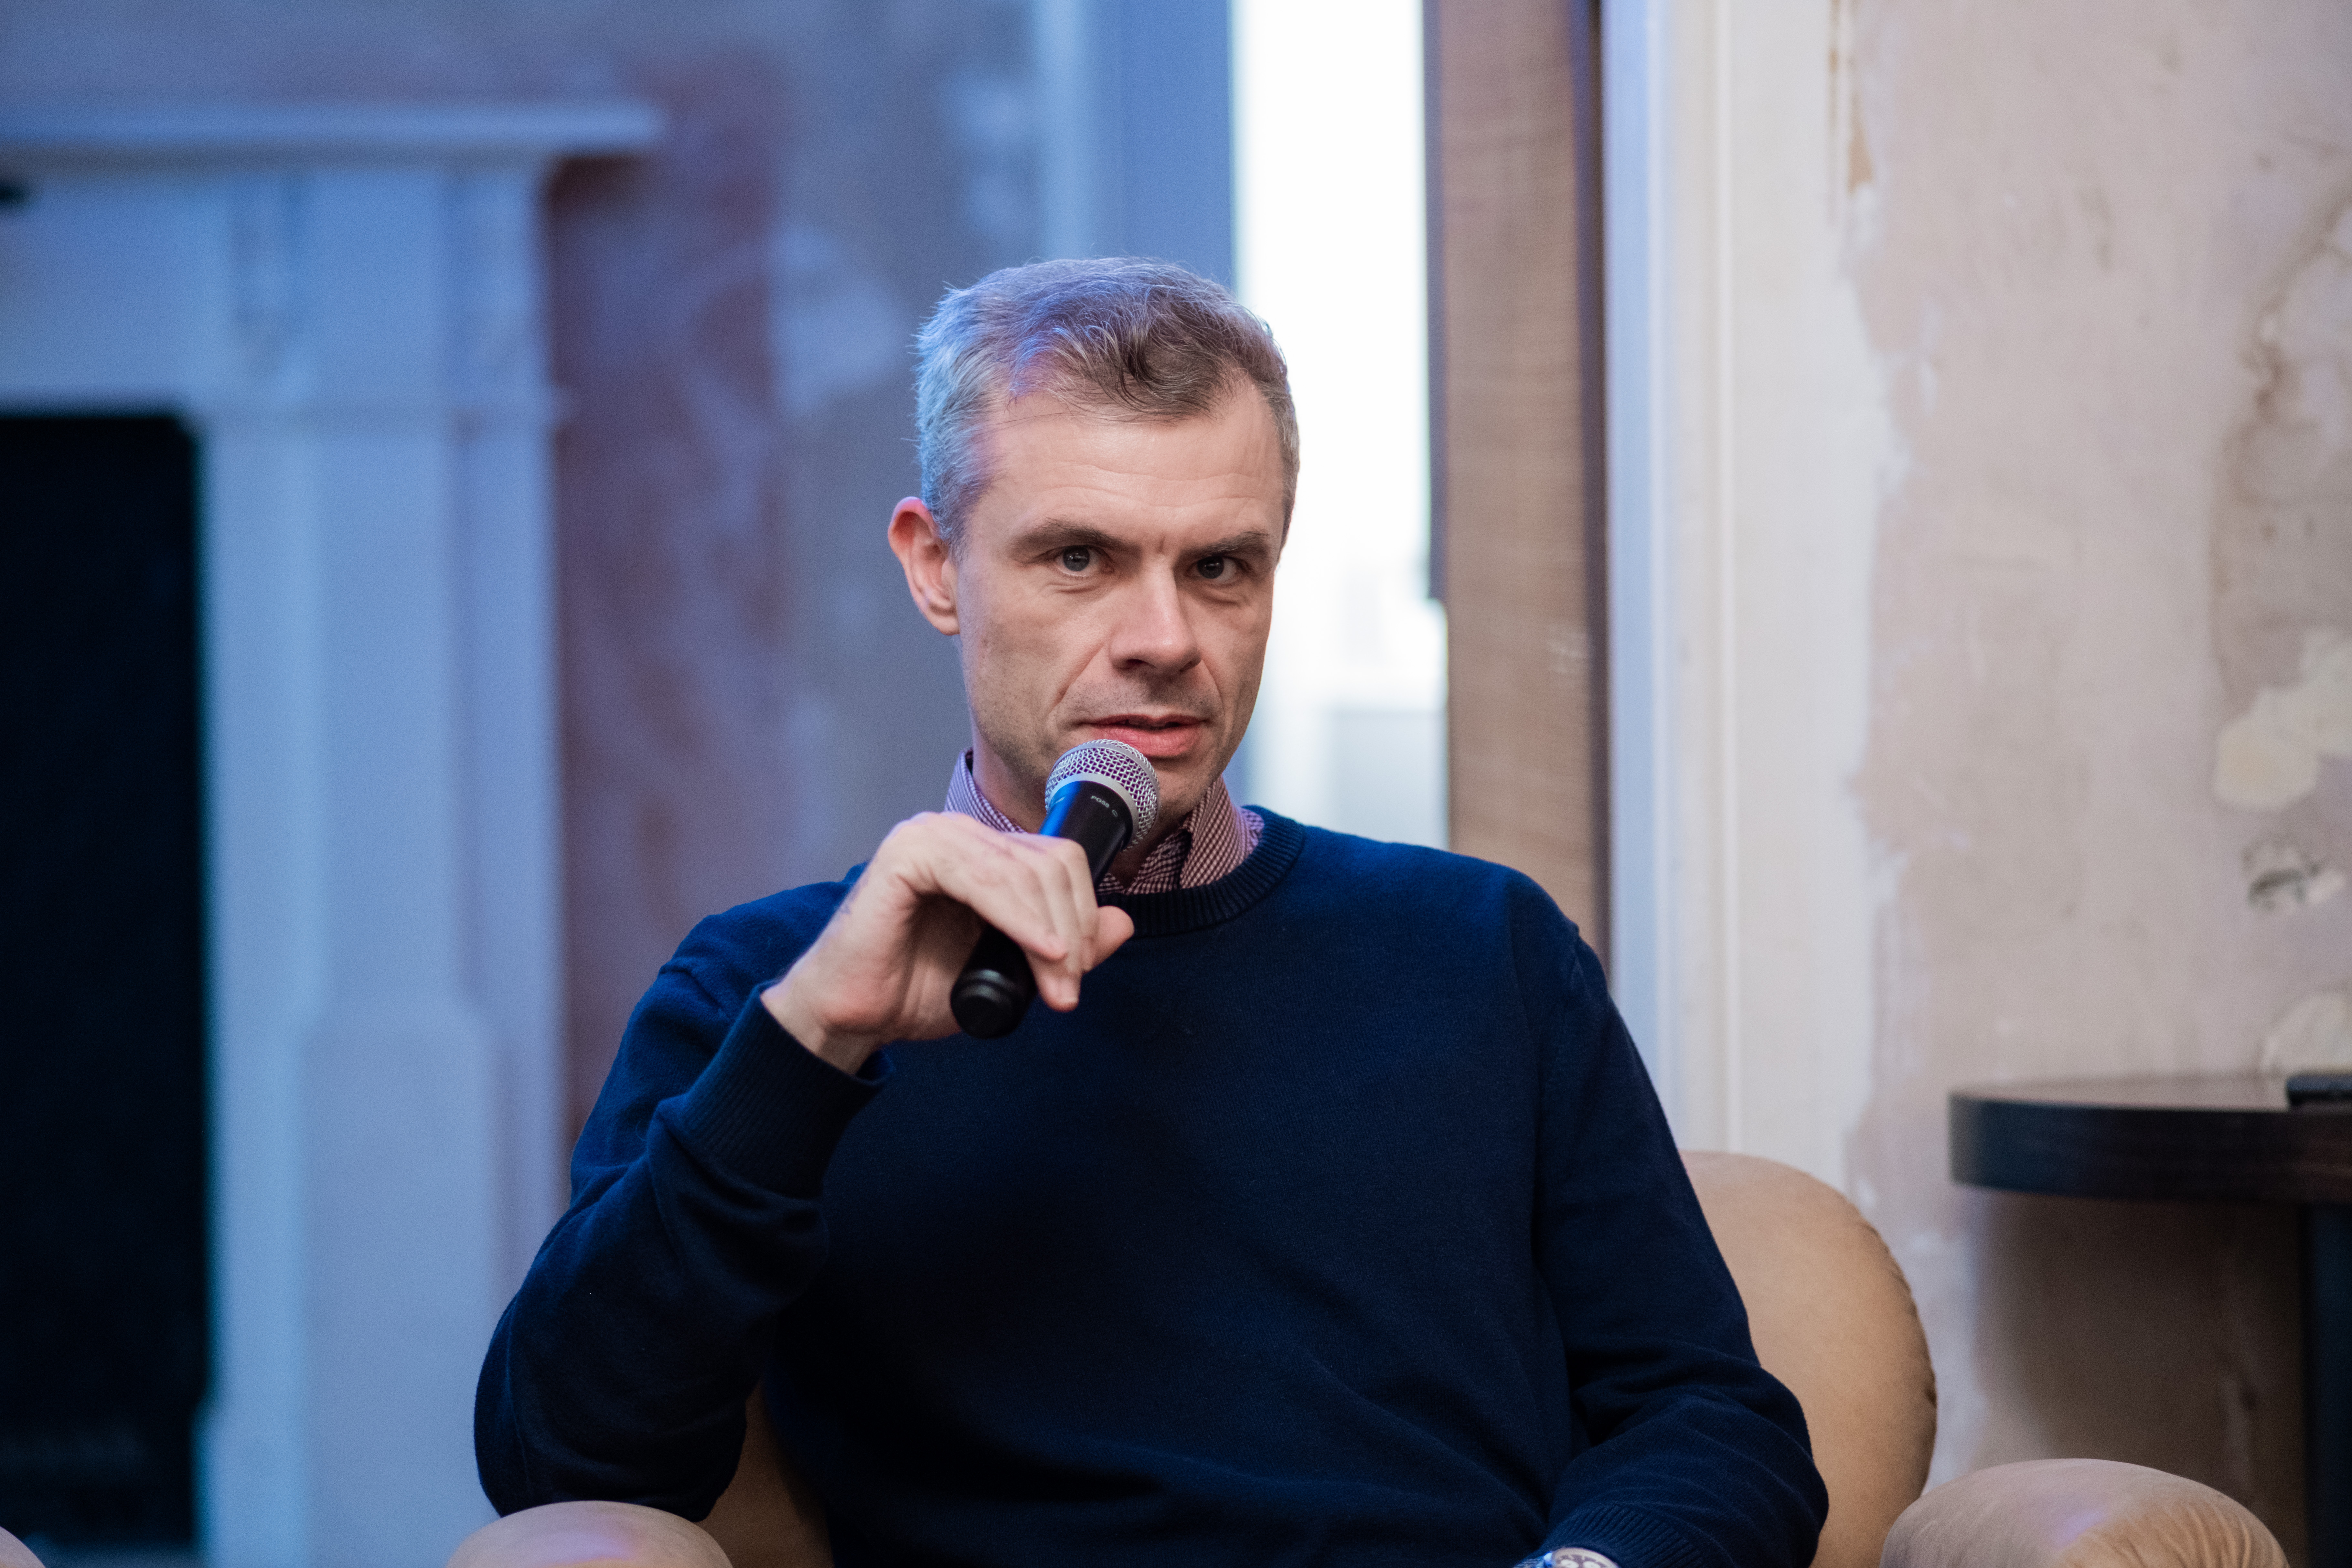
“Your system needs to have some sort of memory of what has happened before.”
Iain Armstrong, Executive Director, FCC Strategy, ComplyAdvantage
Profile the customer, not just the payment
Real-time monitoring only works if the groundwork is done before and after the transaction. Build a customer risk profile, score it, and weigh your business rules against it, and the real-time check has something meaningful to measure against. My normal behaviour is not your normal behaviour – what matters is the moment a customer starts to deviate from their own pattern.
That profiling now reaches well beyond the transaction itself, into how someone interacts with the system: the devices they use, how fast they type, the patterns of access that are hard for an imposter to fake.
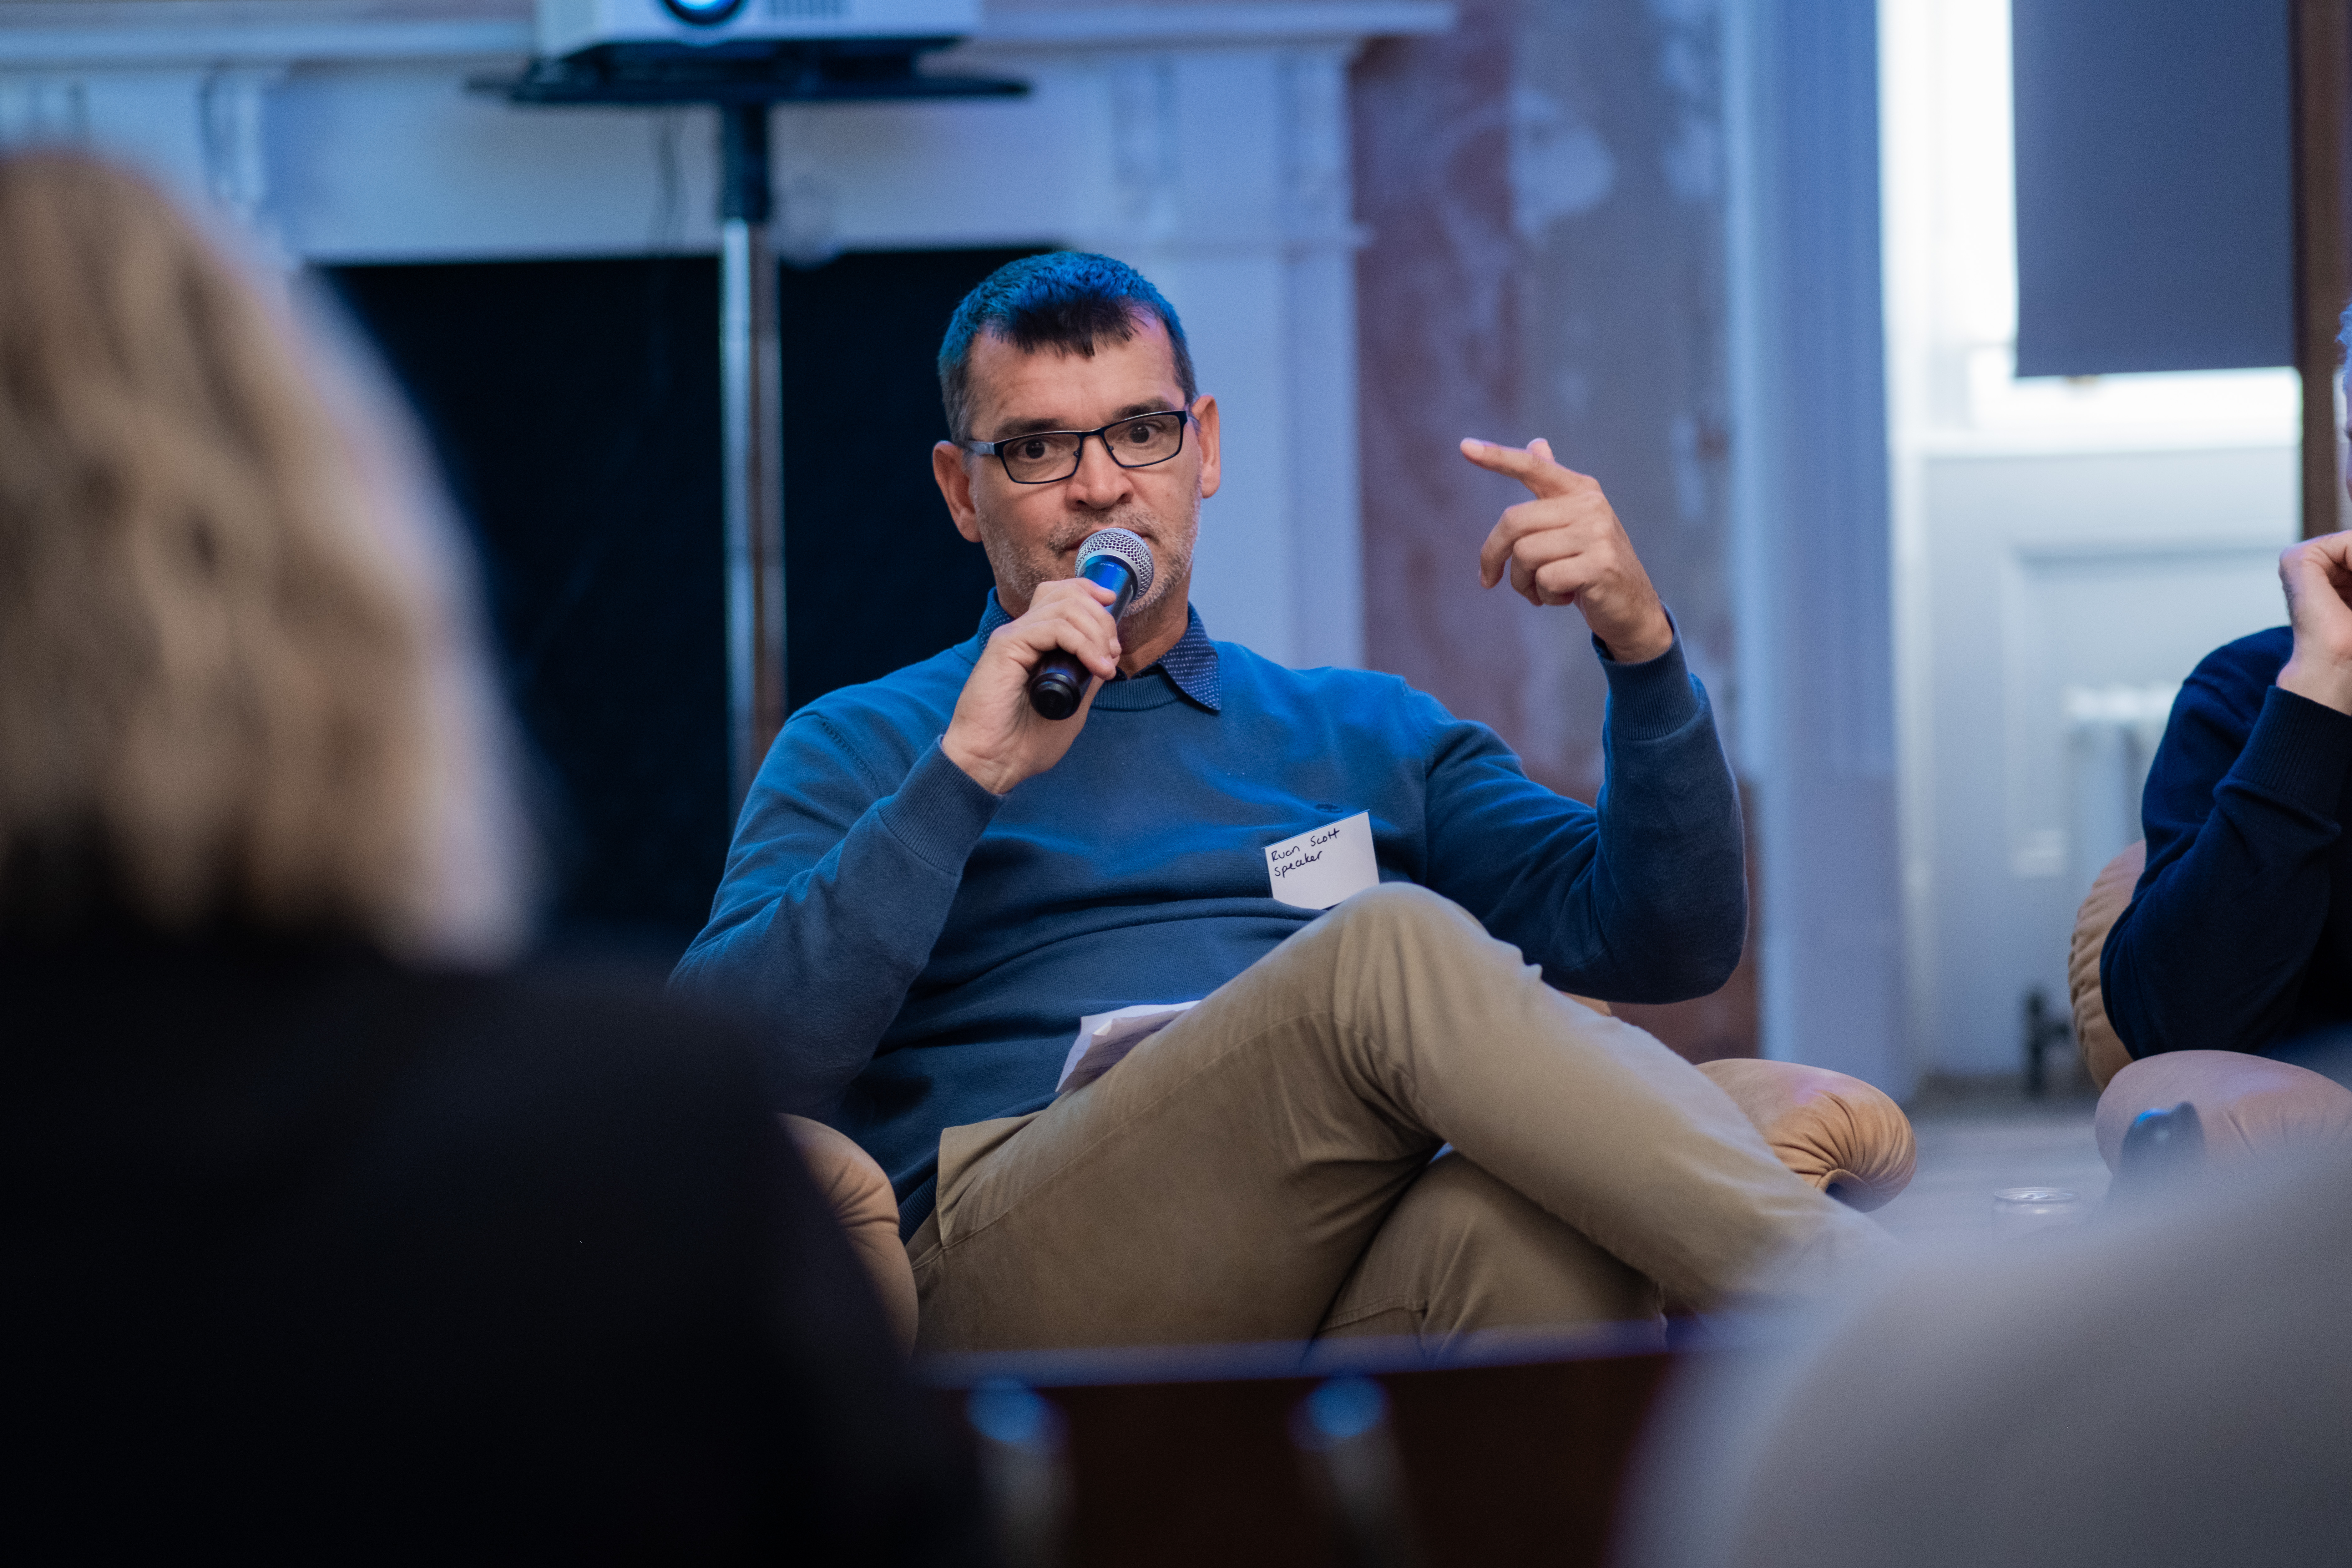
“ You cannot be reactive to financial crime by having a bunch of business rules. You need to have something that evolves.”
Ruan Scott, Regional Managing Director, Prospero AG
Sharing data when the clock is running
The reimbursement regime has changed the operational picture, splitting liability between sending and receiving firms and putting a two-hour notification window in play. For the big banks, the communication channels have existed for years. For smaller firms, paytechs and fintechs, the need to share information fast was a rude awakening – and one they have had to answer quickly.
The fraud is migrating too. As domestic controls tighten, criminals push funds straight overseas, beyond the reach of the regime, often using vulnerable people as the conduit. The defence is partly technical and partly human: training the first line to recognise a scam in progress, and being patient enough to walk a frightened customer through why their own money has been held.
“Safety and speed are not trade offs.”
Iain Armstrong, Executive Director, FCC Strategy, ComplyAdvantage
The takeaway
Fighting financial crime in real time is less about a single clever algorithm and more about memory, profiling and fast collaboration. Hold the right data, understand what normal looks like for each customer, and build systems that evolve as the fraud does – and you can keep customers safe without losing the speed they came for.
The Scaling Checklist
Give your system a memory. Flag dormant accounts that suddenly stir and low-value test payments that precede a large transfer, so past behaviour informs the present decision.
Profile before you monitor. Build and score a customer risk profile pre- and post-transaction so your real-time checks have a baseline to measure deviation against.
Look beyond your own data. Pull signals from across the business – even marketing teams know a lot about how real customers behave.
Train the first line. Most fraud is caught or missed at the human front line; run sessions with real cases so staff know exactly what to look for.
Use the two-hour window. Build the relationships and the rails to share fraud intelligence fast, because recovery depends on speed.
These perspectives are drawn from a Fintech Fringe panel on fighting financial crime in real time, moderated by Lucy Heavens (Heavens Sent – GTM Services), with Pallavi Kapale (Bank of China), Iain Armstrong (ComplyAdvantage) and Ruan Scott (Prospero AG).
Get Involved with Fintech Week London
Attend • Exhibit • Speak • Sponsor • Host
Fighting financial crime in real time is one of the conversations on the Trust as Currency track at this year’s Summit, themed Growth + AI. Fintech Week London runs 7–11 September: five days across the city, built around the two-day Summit on 9–10 September, where founders, investors, operators and regulators come to connect, collaborate and do business in the world’s number one fintech ecosystem.