DeFi Is Not Dead: What Decentralised Finance Actually Offers Fintech Builders Now
DeFi didn’t die in 2022. It morphed – into infrastructure that banks, payments firms and treasurers are now building on. The opportunity for fintech builders isn’t speculation; it’s 24/7 settlement, programmable money and a new way of managing liquidity.
For many in financial services, decentralised finance still conjures images of collapsed exchanges and anonymous traders. But the definition is simpler than the reputation: financial services such as lending and borrowing, built on public blockchains, using code instead of intermediaries.
What has changed is the blurring of boundaries. Banks are moving into tokenisation, crypto firms are applying for banking licences, and infrastructure players sit in between. DeFi hasn’t disappeared – it has changed shape.
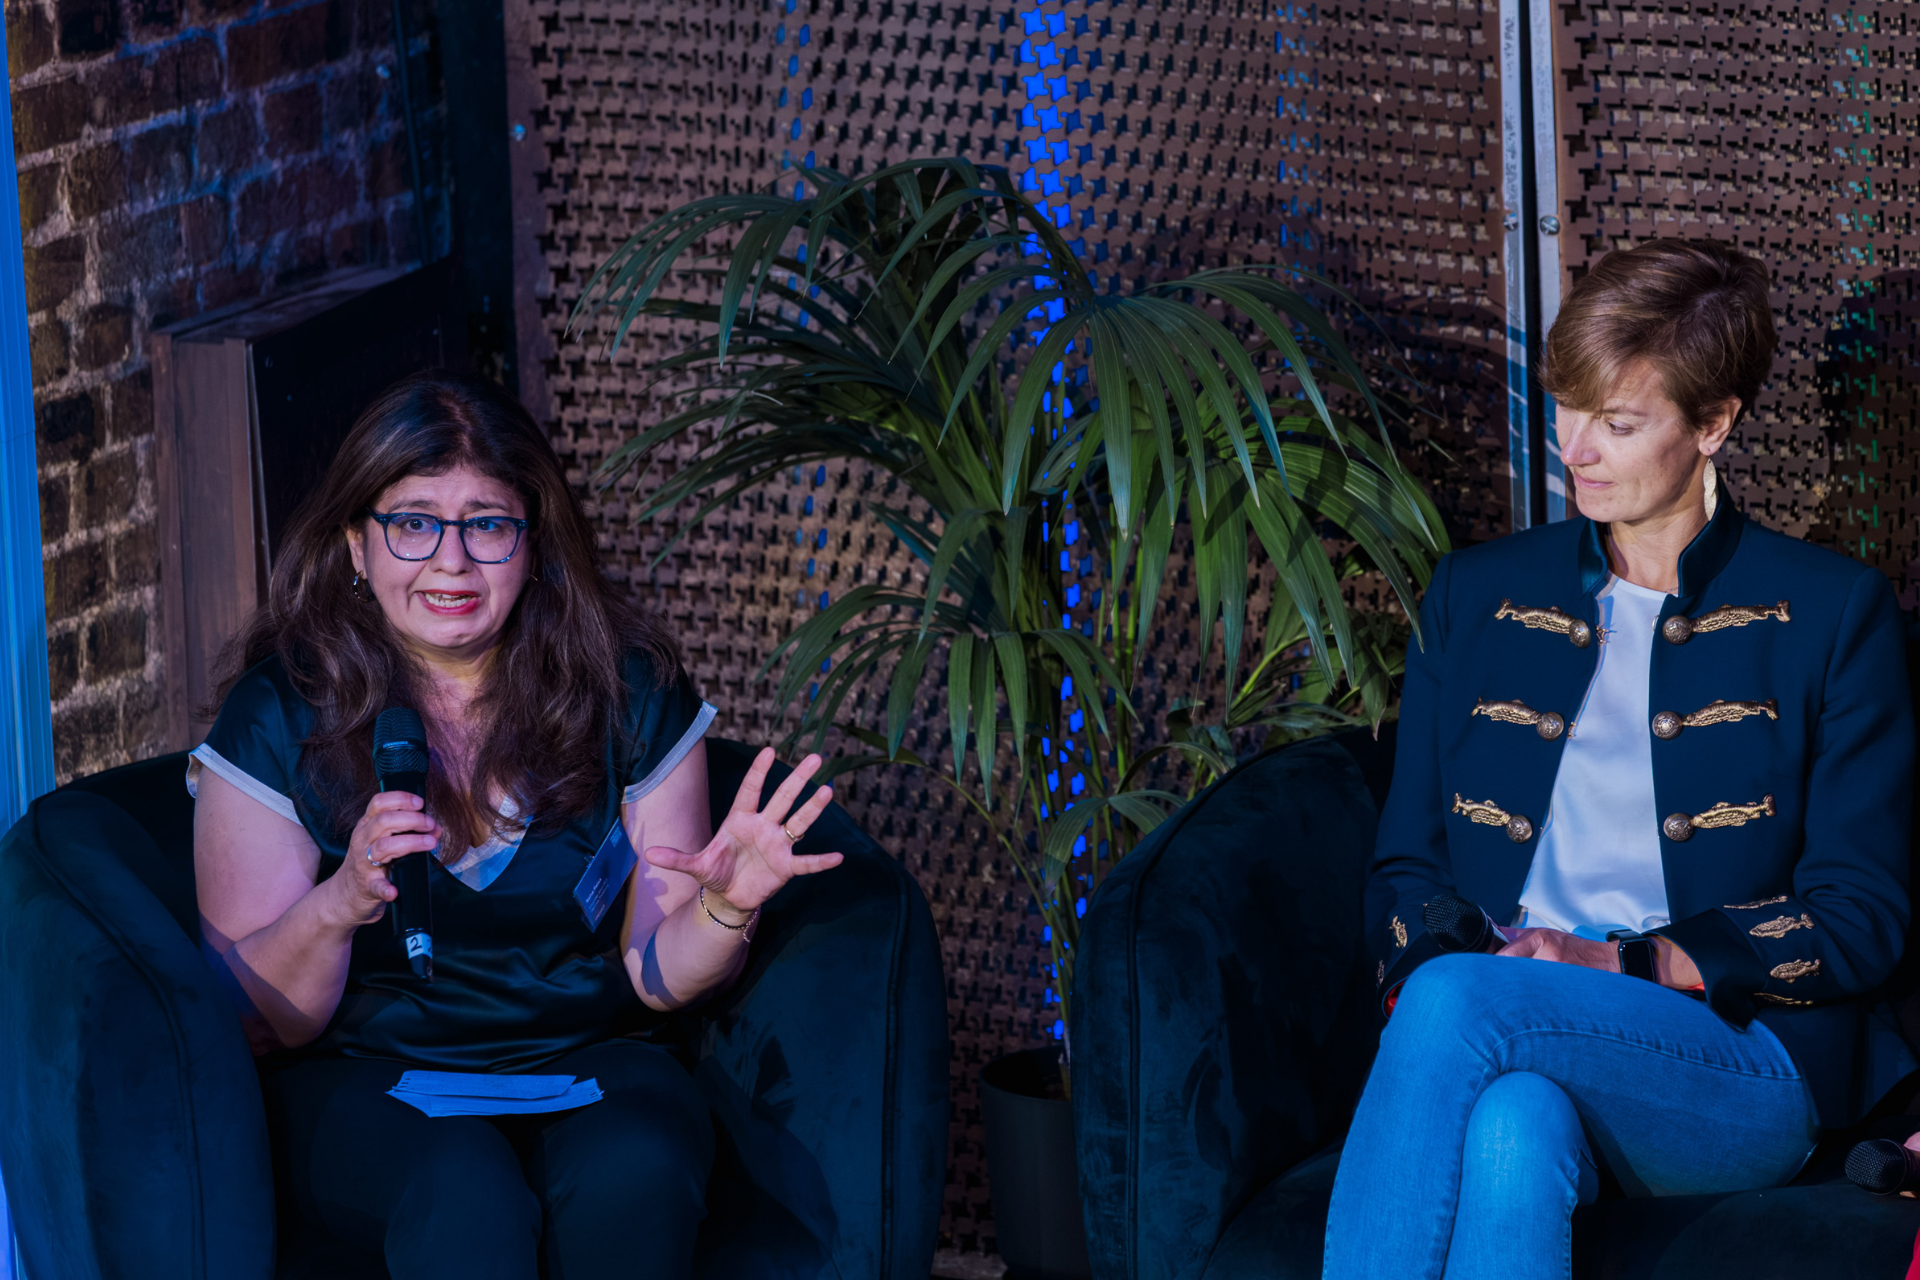
“DeFi is definitely not dead. I think it’s risen from the ashes of the 2022 missteps. But it’s morphed. Banks have made forays into tokenisation, crypto companies are looking to get banking licences – it’s all blurring.”
Neha Reiss, Treasurer and former Monzo executive (Moderator)
Moving beyond the crypto myth
The biggest misconception about DeFi is still that it’s a playground for criminals. The reality looks very different. Platforms such as Hyperliquid are now serious players – small teams competing head-on with listed companies employing hundreds of people – offering round-the-clock trading, micro-loans and micro-credit that traditional finance struggles to provide.
Nor is it slow, expensive or anti-bank. The banks are all over it: Kinexys, JPMorgan’s private blockchain, handles trillions in flows, and Qivalis – the euro stablecoin backed by 37 banks – expects DeFi to be one of its first use cases.
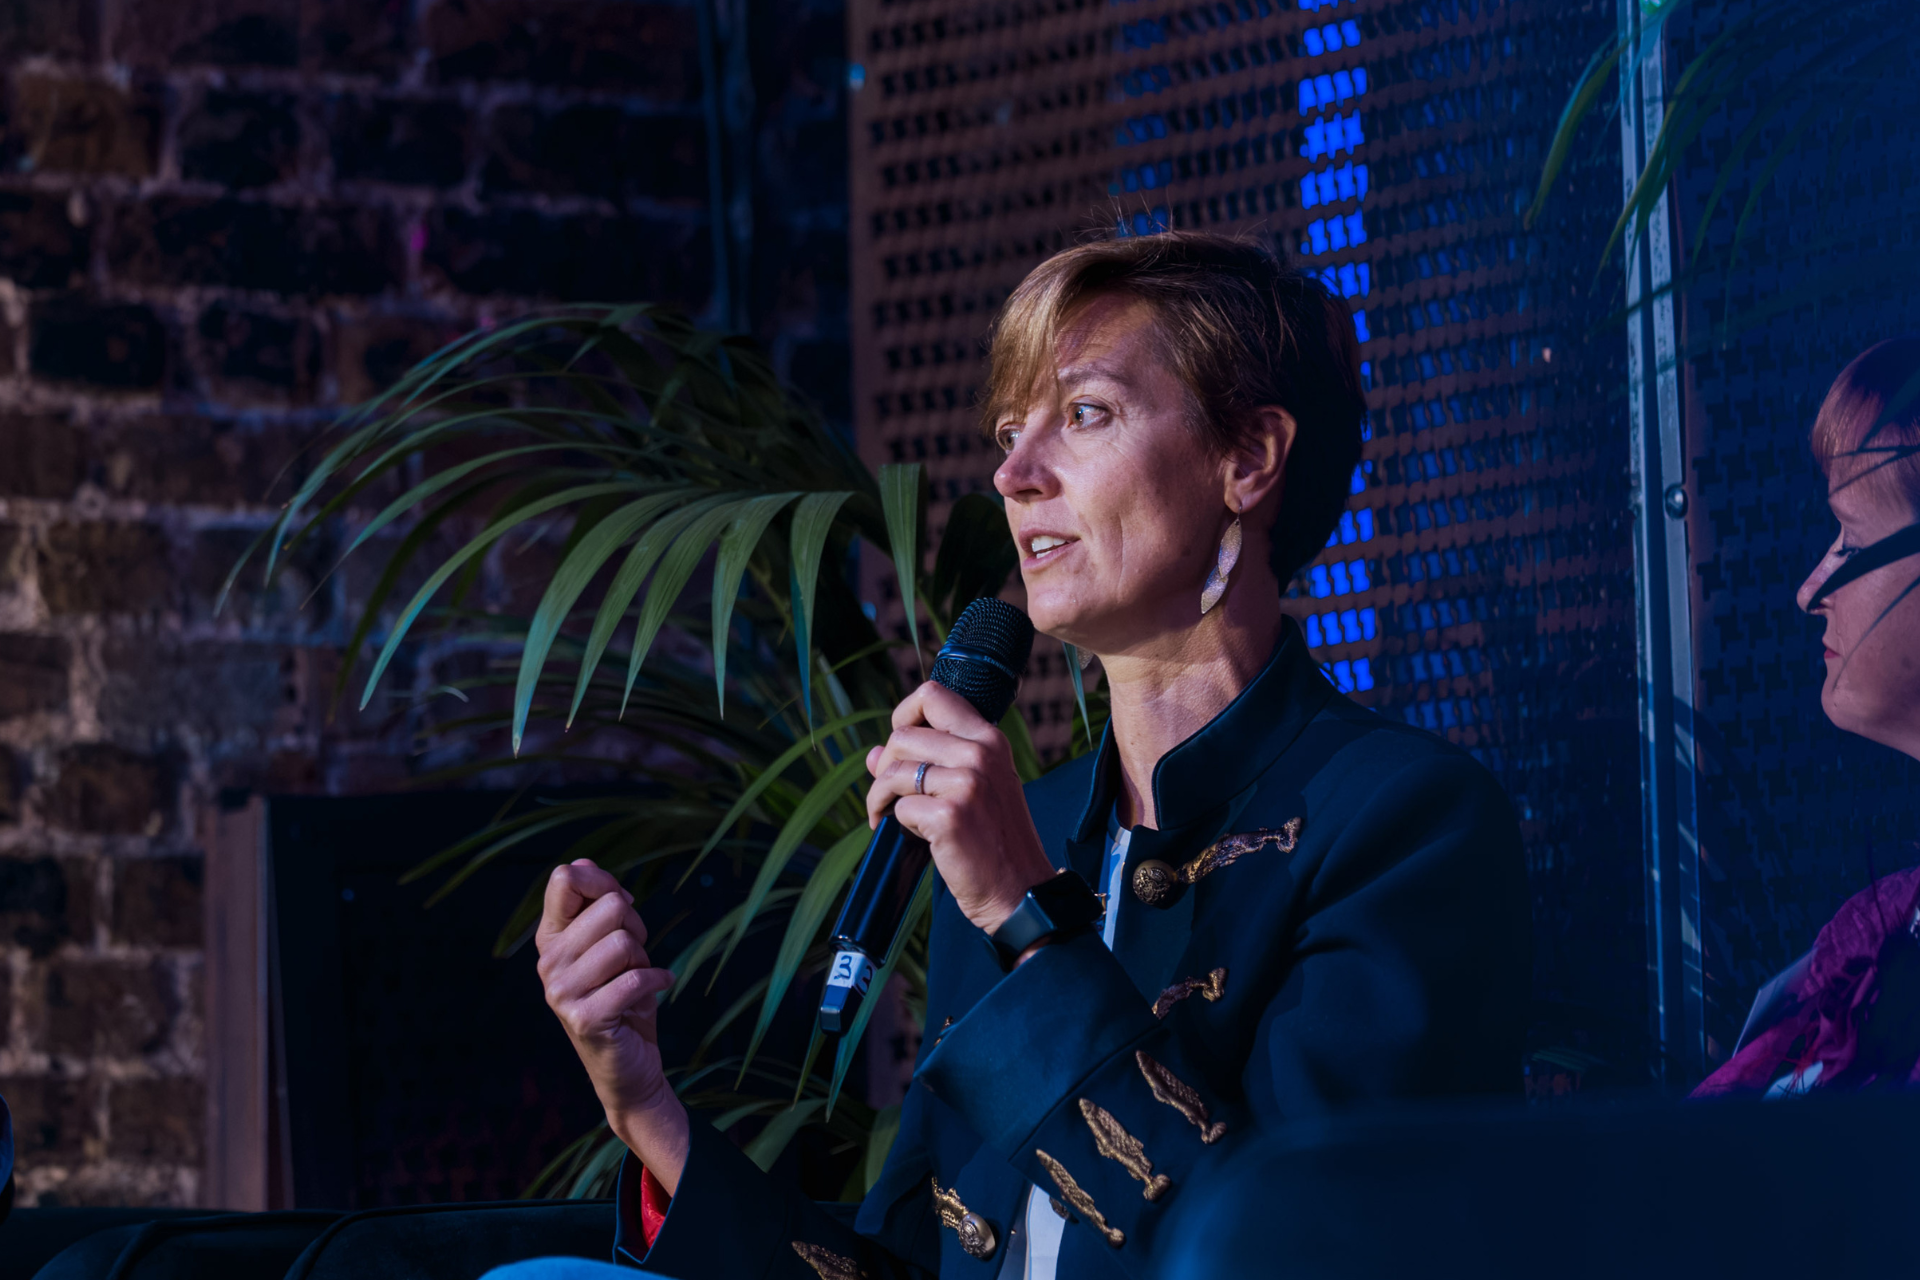
“The biggest misconception is still that it’s for criminals. With teams of 40 people, players like Hyperliquid end up challenging listed companies with hundreds of people. You can trade 24/7, you don’t need all those intermediaries, and you can do things the traditional world cannot do. It’s time to wake up from that.”
Marieke Flament, Currency of Power
Programmable money meets AI agents
The fundamental power of blockchain is the programmability of money: if this happens, then do that. That logic is a natural fit for AI agents. Traditional finance has spent years trying to keep bots out; DeFi is the one environment ready to work with them.
The rails are already forming. Coinbase is developing x402 as payment rails for agents. Stripe has launched Tempo and Circle is building Arc – in part because banks don’t want every customer transaction visible on a public chain.
“The power of blockchain is the programmability of money – if this happens, then that. That’s a perfect match with machines and AI agents. We used to call AI agents bots, and we don’t want bots in traditional finance. But no one is actually ready to work with them except DeFi.”
Marieke Flament, Currency of Power
Where it’s working today
The clearest wins are practical: real 24/7 settlement, continuously verifiable reserves rather than a PDF attestation, and faster, cheaper remittances. Correspondent banking – slow, layered and expensive – is exactly the kind of process the technology is built to improve.
Treasury is where the case is most concrete. With no batch windows, firms no longer need to hold buffers on top of buffers. Intercompany balances can settle around the clock, and idle cash can move into intraday repo or tokenised money market funds instead of sitting still.
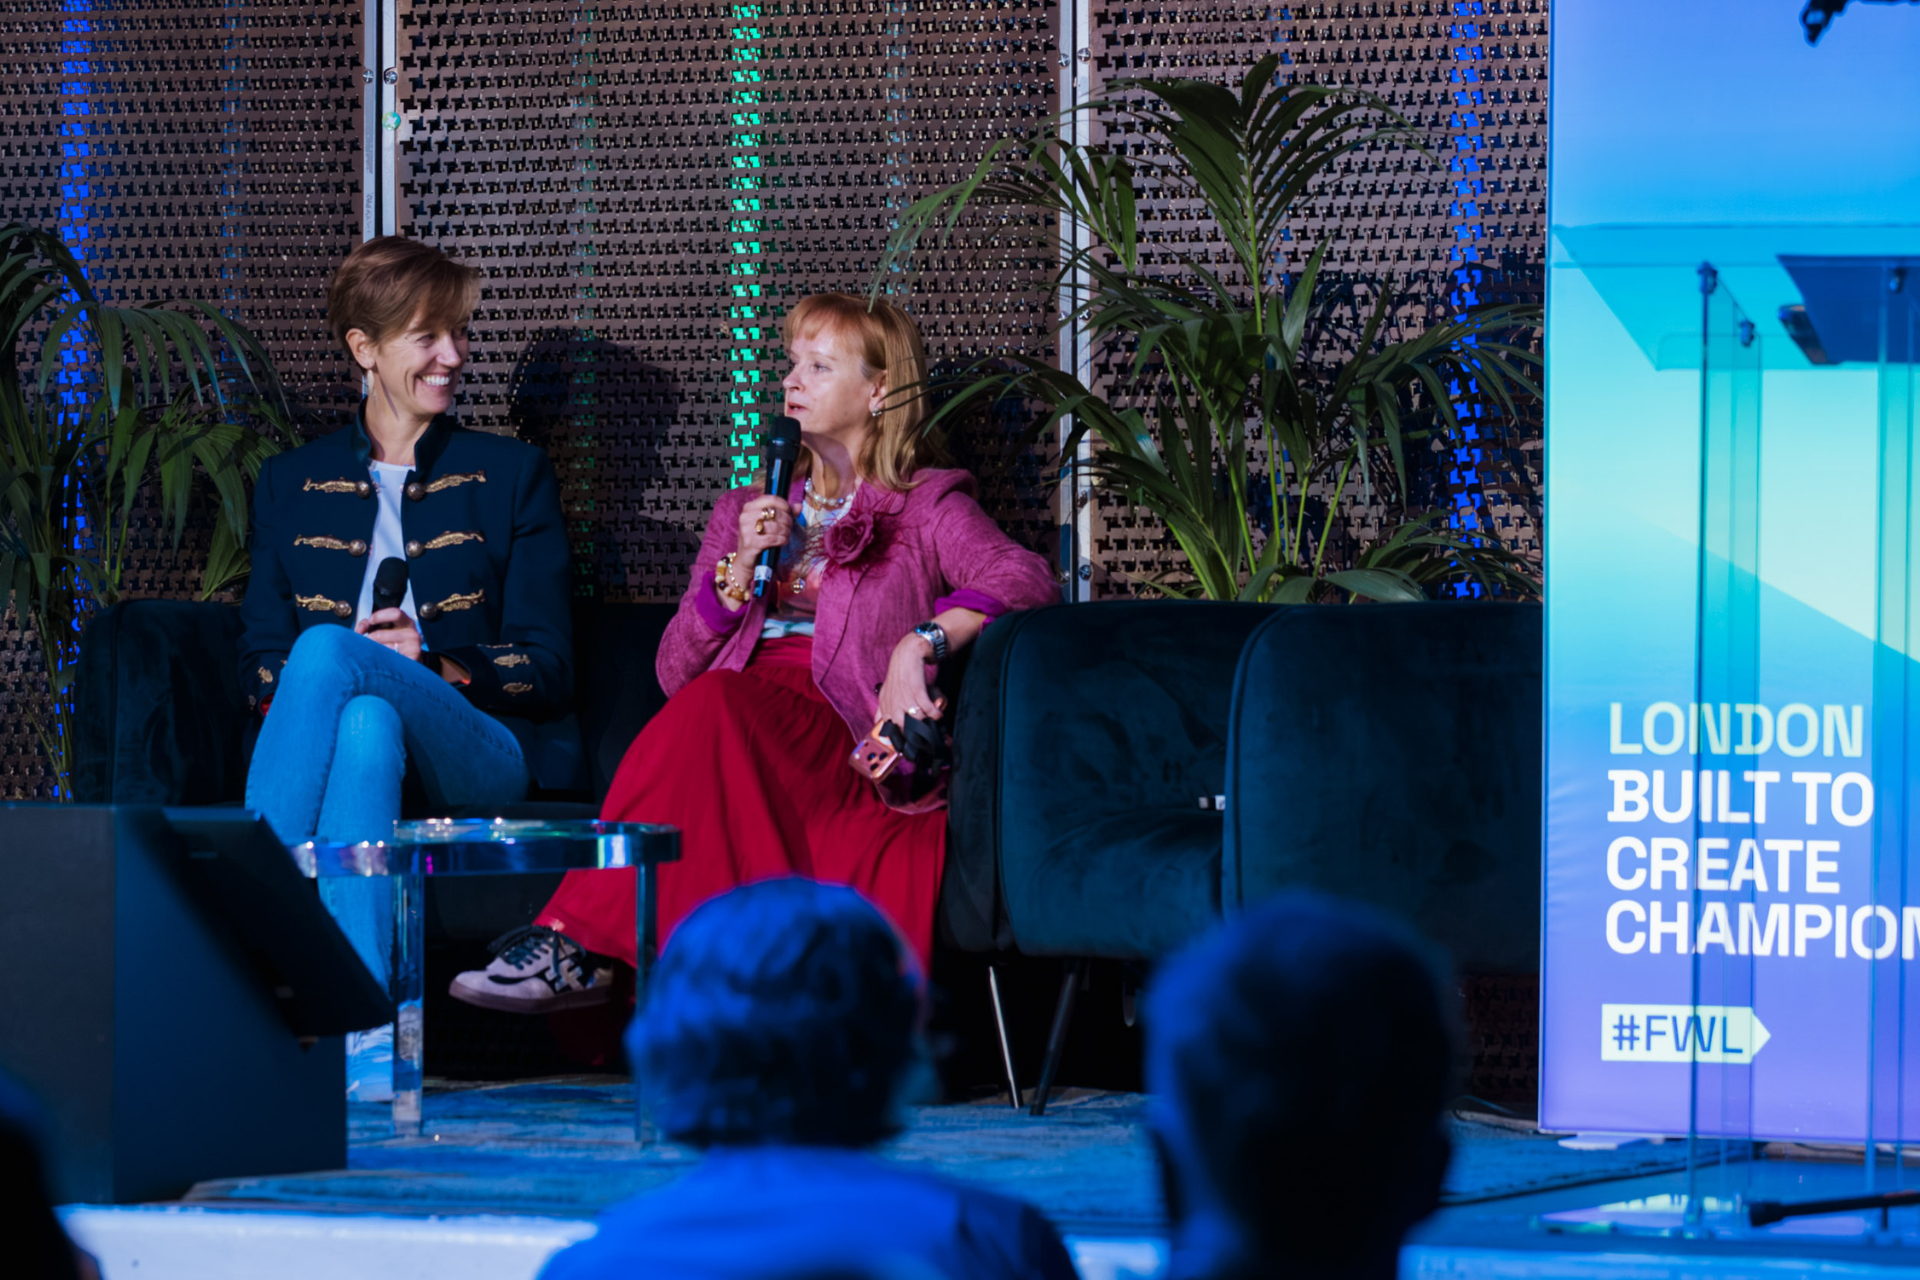
“Real 24/7 service – UK Faster Payments is instant, but that’s not everywhere. And verifiable reserves: rather than a PDF saying it’s been attested, you’ve actually got continuous verification.”
Louisa Murray, FRAME
What’s still in the way
Regulation is arriving, but unevenly. The US GENIUS Act, Europe’s MiCA and regimes in Hong Kong, Singapore and the UK all differ. Regulators also want someone accountable, while DeFi’s founding claim is that there is no one – it’s code.
Operational readiness and user experience remain hurdles too. Liquidity risk for stablecoins and tokenised assets needs to be modelled differently, and a decade in, the products still aren’t user-friendly enough.
“Regulators want to know who they can call. They want someone responsible. One of the claims of DeFi has been: there’s no one, it’s code. Our entire financial system has been built on asking banks to check stuff. In DeFi you have different tools – but you don’t do it the same way. What’s the right model for that?”
Marieke Flament, Currency of Power
The takeaway
DeFi isn’t dead, and it isn’t just crypto. It’s becoming a layer of financial infrastructure – programmable, always on and increasingly bank-backed – that fintech builders can use today for settlement, treasury, remittances and reserves. Regulation, operational risk and UX still stand in the way, but the builders who understand it now will be best placed to shape where finance goes next.
The Scaling Checklist
Start with the problem. Does 24/7 settlement, verifiable reserves, cheaper remittance or programmable money solve something real for you? If so, go for it.
Put your treasury hat on. Map where you hold idle cash and buffers today, and test whether tokenised deposits, stablecoins or tokenised money market funds could put that liquidity to work.
Stress-test before you scale. Model liquidity and operational risk for an always-on world, and plan for different regulation across the US, EU, UK and Asia.
These perspectives are drawn from a Fintech Week London panel on decentralised finance, with Neha Reiss, Marieke Flament (Currency of Power) and Louisa Murray (FRAME).
Fintech Week London 2027
Fintech Week London returns 20-24 September 2027: five days across the city, built around the two-day Summit on 21-22 September, where founders, investors, operators and regulators come to connect, collaborate and do business in the world’s number one fintech ecosystem.