Architecting the Capital Stack: Avoiding the "Crocodile"
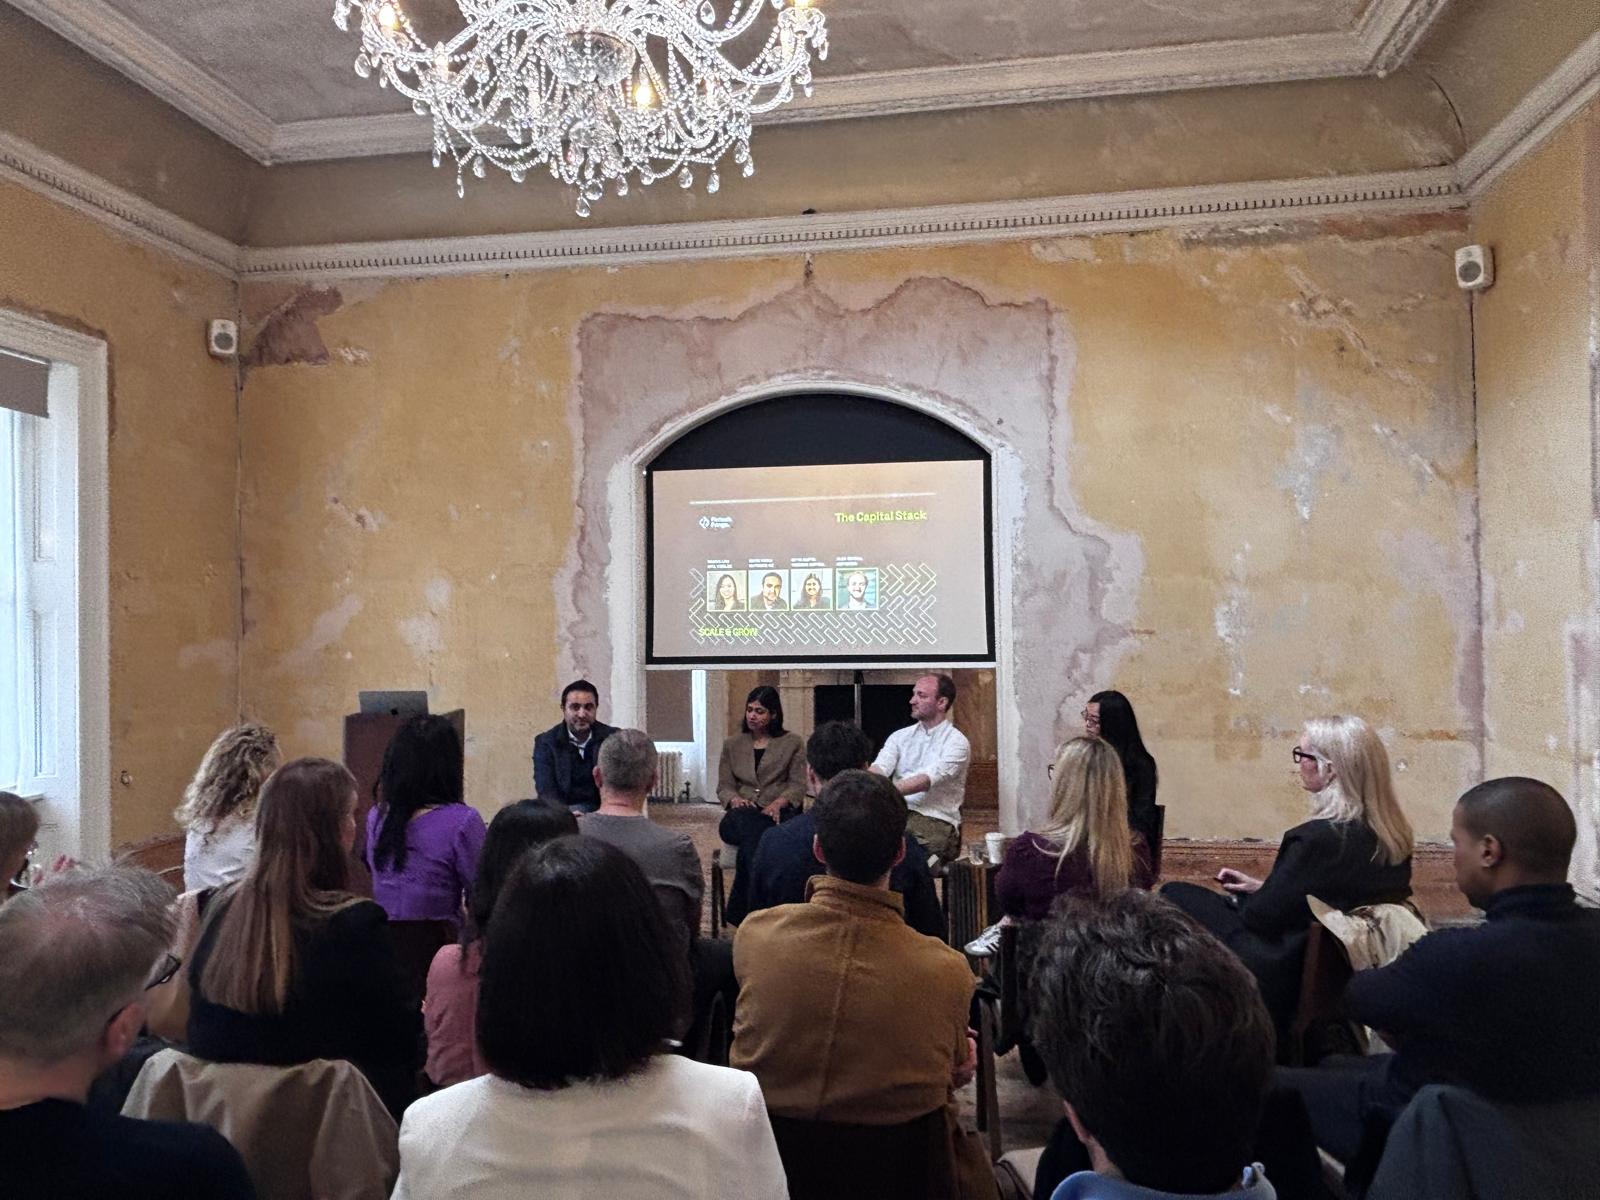
Insights from Scale & Grow: Funding Readiness. Session moderated by Regina Lau, featuring Alex Mayall (Anthemis), Devin Kohli (Outward VC), and Nitya Gupta (13books Capital).
In 2026, the "Capital Stack" is no longer a straight line to the next equity round. As equity becomes more expensive and dilution becomes a central concern for founders, the most resilient fintechs are assembling a "blended" stack of venture equity, strategic corporate investment (CVC), and venture debt. In this tactical panel moderated by Regina Lau, investors from Anthemis, Outward, and 13books explored how founders can fund growth without sacrificing long-term control.
The "Crocodile" Warning: The CVC Trade-off
The panel explored the double-edged sword of bringing a bank or a payment rail (a "strategic") onto the cap table. While a strategic investor offers "unfair advantages" in distribution and credibility, they also introduce massive structural risk. Devin Kohli issued a stark warning: "Be wary of the crocodile eating the baby." A strategic investor often has different motivations than a VC-they care about product roadmaps and market share more than pure financial outcomes.
If you give a strategic a "Right of First Refusal" (ROFR), you may inadvertently poison your exit. Future acquirers will be hesitant to bid if they know a competitor can simply match the price and take the deal.
The consensus? Keep strategics to a minority position and ensure they have no "special rights" that complicate the cap table.
Venture Debt: Precision Fuel vs. Financial Tripwires
Venture Debt is having a "moment" in the UK, but it is often misunderstood.
Devin Kohli provided a visceral rule of thumb for founders:
"If you're going to use it to keep doing what you're already doing-something proven with a clear ROI-take it. If you're going to use it to experiment-don't."
Debt is about security, not growth equity. It comes with covenants (financial tripwires) that, if hit, can lead to the lender taking control. For regulated fintechs, this is particularly high-stakes; a debt breach can trigger regulatory alarms that threaten the company’s operating license. Debt should be viewed as a "bridge" to a higher valuation or a tool for predictable marketing spend, but never as a life-raft for a sinking business model.
Valuation vs. Terms: The Quality of the Round
In a tighter market, the panel urged founders to focus on "cleanliness" over valuation. A "down round" or a "flat round" with clean terms is often far better for the long-term health of the business than an "up round" that gives away aggressive liquidation preferences or board control.
Nitya Gupta noted that aggressive terms at Series A can "stack up," making it impossible to raise a Series B because the later investors won't want to sit behind a complex web of previous investor protections. Founders must manage their cap table through to Series B to ensure the team retains enough "skin in the game" (typically 15-20% ownership) to remain motivated for the decade-long journey toward an exit.
The "Great Bundling" and M&A Dynamics
The panel discussed a shifting trend for 2026: "The Great Bundling." As the market matures, technology companies are no longer just buying products; they are buying mental talent and regulatory moats.
Alex Mayall noted that in the age of AI, the ability to "land-grab" talent through M&A is becoming a primary growth strategy for incumbents. For founders, this means the cap table must be structured to allow for an acquisition. If a strategic investor has "veto rights" on a sale, you may find yourself blocked from a life-changing exit because it doesn't align with the strategic's corporate agenda.
The Percentage Myth: Founder Equity Targets
Founders often ask what percentage they should own at each stage. While the panel avoided "pigeonholing" specific numbers, the consensus was that a 20% dilution per round is the standard benchmark.
Nitya Gupta advised founders not to over-engineer the cap table to maintain a specific number if it comes at the cost of the right partner. However, if the founding team’s stake is diluted too aggressively at Seed or Series A, institutional investors at later stages may see it as a "red flag," fearing the team lacks enough upside to survive a 10-year grind.
Unit Economics: The "Investability" Floor
Finally, the panel defined the "New Normal" for fintech efficiency. For payments companies, a 35% gross margin is now considered the floor, while AI-driven fintechs are being pushed toward 60-70% margins. Beyond just "revenue," investors are now conducting deep-dives into NRR (Net Revenue Retention) and pipeline conversion.
If you can’t prove that your existing customers are growing their spend, you don't have a venture-scale business. Investors are looking for "unbribable" moats-licensing, IP, and regulatory expertise-that protect these margins from being eroded by the next wave of "vibe-coding" startups.
The Scaling Checklist
Strategic Rights Audit: Ensure legal counsel scrubs term sheets for ROFRs or veto rights. You want their distribution, not their permission to sell.
Gross Margin Discipline: If your gross margins are below 60% for software or 35% for payments, your business is not "venture-scale" in 2026. Audit your COGS today.
NRR/ACV Focus: Prove that your existing customers are growing their spend. Net Revenue Retention (NRR) is now as important as new logo acquisition.
The "Skin in the Game" Map: Aim for no more than 20% dilution per round. If you are diluting faster, you risk being "uninvestable" by Series B.
Debt for Proof, not Discovery: Only take venture debt once your "customer acquisition engine" is proven. Debt should fund a machine that works, not help you find the machine.
Want support with your fundraise?
Get in touch with Calypso: calypso@fintechfringe.co